Published by SencoProperties News. This is general information, not legal, surveying, valuation, tax or financial advice. Requirements and circumstances vary; confirm your specific case with the relevant authority and qualified professionals.
Real estate investment in Ghana can take several forms: buying land for future use, purchasing a completed home to rent out, renovating an existing property or developing a building.
These strategies have different cash requirements, time horizons, legal checks and risks. A sensible decision starts with the investor’s objective and capacity, not a promise that property values will always rise.
Define the purpose of the investment.
Decide whether you want recurring rental income, long-term capital growth, a future home for your family, a development profit or a combination. Each objective changes the appropriate property and location. Rental income depends on achievable rent, vacancy, repairs and management costs. Land held for appreciation may generate no cash flow while expenses continue. Development can produce a sale or rental asset but adds construction, approval and delivery risks. Write down the intended holding period and the conditions under which you would sell or change strategy.
Understand the main investment choices.
Vacant land may require less immediate maintenance than a building, but it can still involve security, boundary, clearing, tax, ground-rent or other holding costs depending on the interest and circumstances. A completed rental home may produce income sooner but requires tenant management, repairs and vacancy planning. Renovation can add value if the cost and likely demand justify it, but hidden defects can undermine the budget. Development offers more control over design but requires experienced professionals and careful oversight. None is automatically safer or more profitable than the others.
Build a full cost model.
List the purchase price, legal fees, official searches, survey, valuation, registration, applicable taxes or duties, financing, insurance, repairs, utilities, service charges, management and sale costs. For land, add site security, access improvements and any costs necessary before it can be used. For rental housing, include vacancy, tenant turnover, painting, plumbing, appliance replacement and emergency repairs. For development, include design, permits, contractor payments, materials, supervision, utility connections and a contingency for delays or cost increases.
Do not confuse asking price with market value.
Online listings show what sellers hope to receive, not necessarily what buyers ultimately pay. Compare properties that are similar in location, size, legal status, access, condition and permitted use. Seek advice from a qualified valuer when the amount justifies it. Ask how a valuation was reached and what evidence supports the comparison. A high price per square metre in one neighbourhood cannot automatically be applied to another area or a different property type. Record the date of every comparison because market conditions can change.
Assess rental income realistically.
Estimate rent using comparable homes with similar condition, amenities and access. Then subtract realistic operating costs and allow for periods without a tenant. Do not assume that every month will be paid on time or that a property will never need major repairs. Calculate the annual net operating income before financing and compare it with the total capital invested. If the result only looks attractive when every room is occupied and no repairs occur, the investment may be too fragile for your risk tolerance.
Understand tenant demand and property management.
Consider who is likely to rent the home: families, students, workers, businesses or short-term visitors. Different tenant groups value different locations, layouts, security arrangements and transport links. Ask how quickly comparable units are let and what improvements tenants expect. Decide who will handle viewings, screening, agreements, repairs, rent collection and disputes. A professional manager charges a fee but may save time; self-management still has a cost in hours and availability. Avoid projecting premium rent unless the property’s features and location support it.
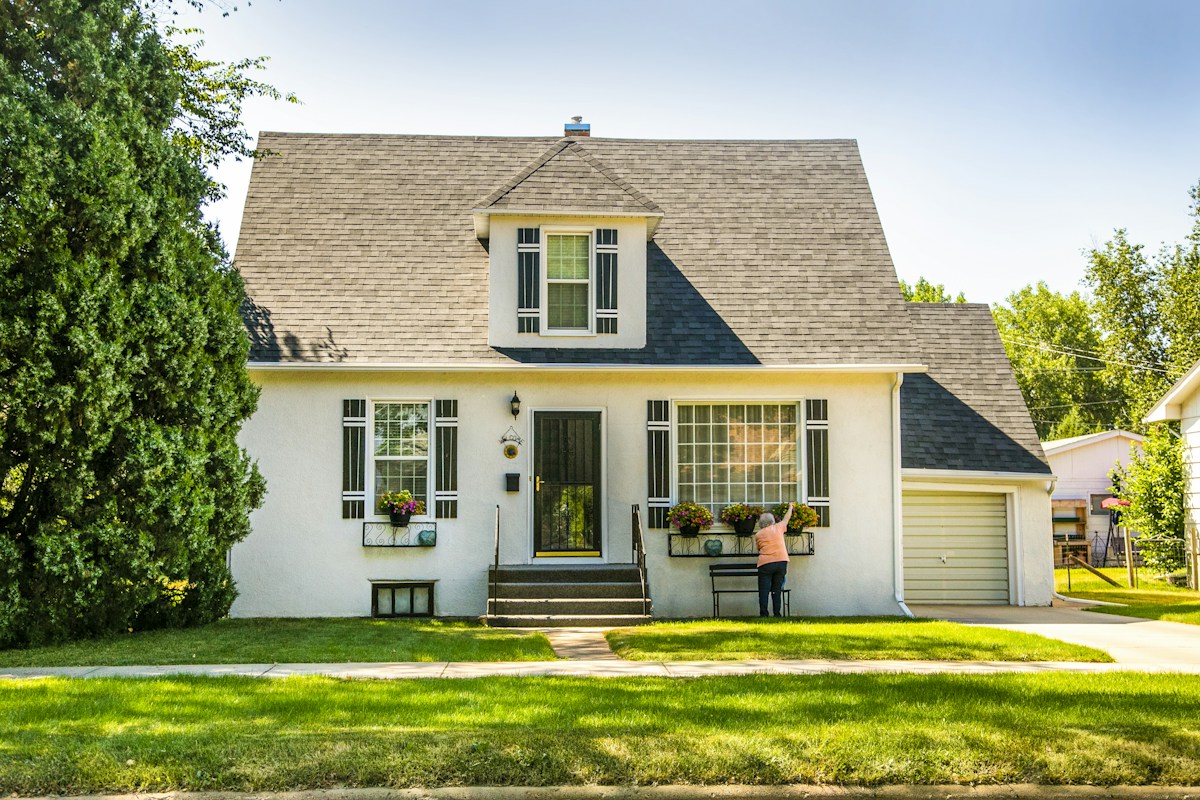
Residential home illustrating property investment, inspection and ownership considerations.
Land investment requires legal and physical due diligence.
Verify the seller’s authority, the nature and duration of the interest, the site plan, boundaries, access, planning restrictions and any required consents. Obtain the appropriate official search and have a lawyer interpret it. The Lands Commission’s registration guidance describes important documentation requirements, while its online services portal provides a starting point for relevant services. A vacant plot can still be affected by competing claims, disputed boundaries, access issues or restrictions that limit future use.
Construction and renovation risk
For a building project, obtain a realistic design and specification before comparing contractor quotations. Check the contractor’s experience, references, insurance where applicable, written scope, payment milestones, change-order process and defect responsibilities. Avoid paying the full price upfront without safeguards. Have an independent professional inspect work at meaningful stages. Material prices, weather, labour availability, approval delays and changes to design can affect both timing and budget. A contingency is a planning tool, not permission to ignore cost control.
Financing and interest-rate risk
Borrowing can increase the amount of property you control, but it also creates fixed obligations even when rent is late or a project is delayed. Ask lenders for the effective cost, fees, repayment schedule, security requirements and whether rates can change. Stress-test the investment for lower rent, vacancy, higher repairs and increased payments. Do not base the decision only on the most optimistic income scenario. Keep personal emergency savings separate from money reserved for property expenses so a short-term setback does not force a distressed sale.
Liquidity and exit strategy
Property is not always easy to sell quickly at the desired price. Before investing, ask who the likely future buyer or tenant will be and what evidence supports demand. Consider how location, access, documentation, building condition and financing availability could affect resale. For land, clarify whether a future purchaser can verify and register the interest without unresolved issues. Decide in advance what would trigger a sale, refinancing, renovation or change of use. An exit plan helps prevent emotional decisions when market conditions become difficult.
Taxes, fees and records
Ask a qualified tax professional or lawyer about the tax and registration obligations that apply to the particular acquisition, rental income, development or sale. These can depend on the structure, parties and type of transaction. Do not rely on a social media post or a fee schedule from the old year. The Lands Commission fees and charges page is a useful official starting point for relevant land services, but confirm the current charge and whether it applies to your case. Keep contracts, receipts, invoices, tenant records and professional reports organised.
Compare strategies with the same framework.
Use a table that includes total initial capital, annual operating costs, realistic income, time to income, maintenance needs, legal complexity, financing exposure and likely exit options. Assign conservative, base and optimistic scenarios. The conservative case should test what happens if rent is lower than expected, construction takes longer or resale takes more time. Avoid making forecasts look precise when the underlying evidence is weak. It is better to identify uncertainty than to hide it behind a single attractive return percentage.
Common investment mistakes
- Buying based on a rumour that an area will “boom” without checking planning or demand.
- Ignoring legal and surveying costs when calculating the budget.
- Assuming a property will be occupied continuously.
- Underestimating repairs, security, management and shared charges.
- Starting construction before approvals, scope and funding are clear.
- Borrowing based on optimistic rental or resale assumptions.
- Failing to document agreements and payments.
These mistakes can often be reduced through professional advice, conservative assumptions and written records.
Use official data and independent advice.
For demographic and housing context, explore Ghana Statistical Service’s Population and Housing Census resources. Census information helps describe population and housing conditions, but it should not be treated as a direct prediction of prices or returns for an individual property. Combine broad data with local comparisons, inspections and advice from a lawyer, surveyor, valuer, accountant or qualified building professional as appropriate.
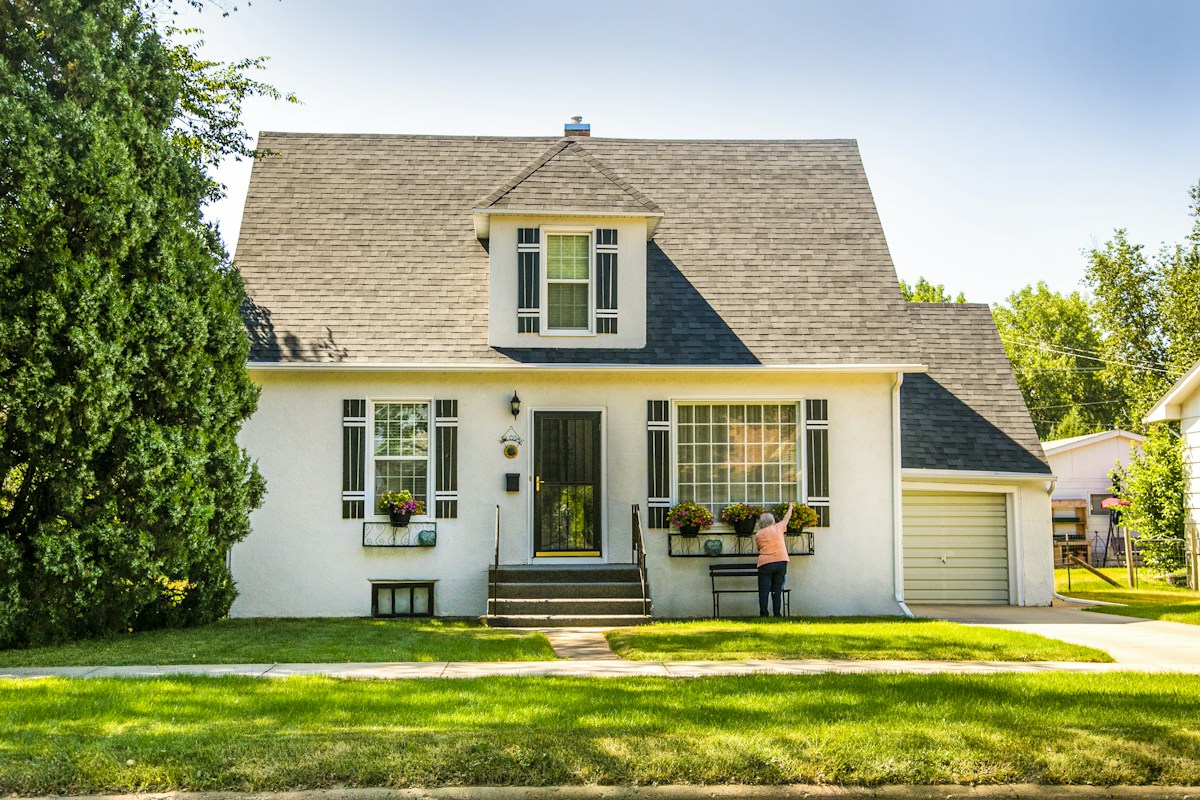
Residential home illustrating property investment, inspection and ownership considerations.
Conclusion
Successful property investing is not guaranteed by owning land or a building. It depends on paying a defensible price, verifying the legal interest, understanding demand, controlling costs, managing risk and having a realistic exit plan. Compare land, rental property and development against your own financial capacity and time horizon. For more Ghana-focused property guides, visit SencoProperties News. This article is educational and not personal investment, legal or tax advice.
Set review points for the investment
After purchase, review the investment on a regular schedule rather than assuming that the original forecast will remain correct. For rental property, track occupancy, rent collected, maintenance spending, overdue amounts and the time required to resolve repairs. For land, keep records of boundary inspections, security costs, rates or other applicable charges and any planning changes relevant to the intended use. For a development, compare actual spending and milestones with the approved budget and schedule, and record each change to the scope. A simple quarterly review can identify a deteriorating position before it becomes a major problem.
Set thresholds that would cause you to reconsider the strategy, such as a sustained increase in vacancy, repair costs that exceed your reserve, a financing payment that is no longer comfortable or a material change to the project’s approvals. These thresholds do not predict the future, but they encourage a timely response. Keep personal finances separate from project records, and consult a qualified accountant or adviser where tax, financing or ownership structure is material. Property investment is a long-term commitment, and protecting capital matters as much as identifying possible returns.
1 Comment
Ghana Building Cost Inflation Reaches 5.1% In September: What Property Owners Need To Know - PROPERTY GHANA DAILY · October 28, 2026 at 9:42 am
[…] quality, service connections, defects, and the cost of completing or maintaining the property. Our guide to comparing land, rental homes and property development offers a broader framework for evaluating property risk and cash […]